Uninsured vs Underinsured Motorist Coverage: Key Differences
Uninsured vs underinsured motorist coverage: one protects you when the other driver has no insurance, the other when their limits are too low. Know the difference.
By Isobel Crane
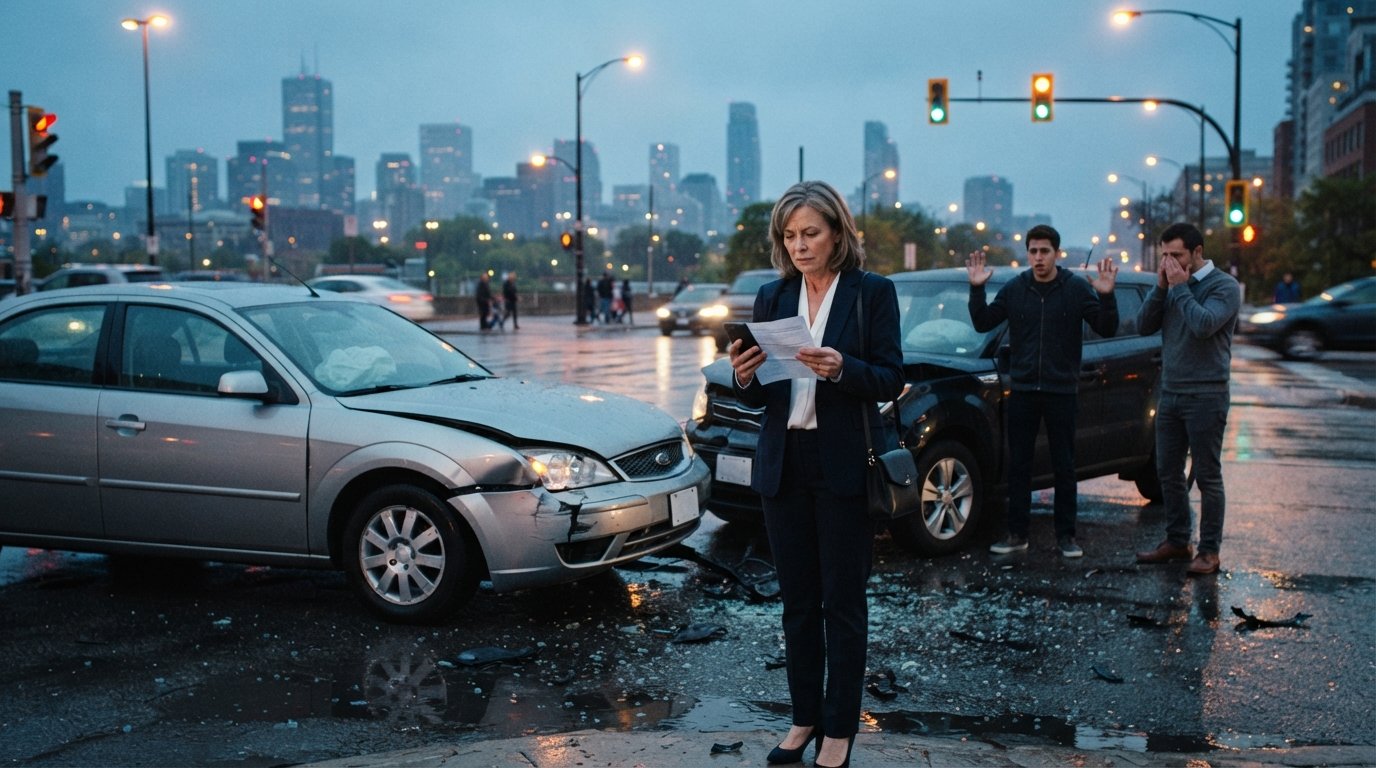
You are driving home from work when another vehicle runs a red light and slams into your car. The other driver is at fault, but when you exchange information, you discover they have no insurance at all. Or perhaps they have insurance, but their liability limits are so low that they cannot cover the cost of your medical bills and vehicle repairs. In these scenarios, your own uninsured or underinsured motorist coverage becomes your financial lifeline. Understanding the difference between these two types of coverage is not just an academic exercise; it is a critical step in protecting yourself and your family from financial ruin after an accident.
Many drivers assume that because auto insurance is mandatory in most states, everyone on the road is adequately covered. The reality is quite different. A significant percentage of drivers operate without any insurance, and even more carry only the state minimum limits, which are often far too low to cover serious injuries or damage. This article will break down uninsured vs underinsured motorist coverage, explain how they work together, and help you decide how much protection you need. We will also explore how these coverages interact with your other policy components and why they are often the most valuable dollars you spend on your auto insurance.
What Is Uninsured Motorist Coverage?
Uninsured motorist coverage (UM) is a component of your auto insurance policy that protects you when you are involved in an accident with a driver who has no liability insurance. It also applies in hit-and-run situations where the at-fault driver cannot be identified. Think of it as a substitute for the liability coverage the other driver should have had but did not. When you file a claim under your UM coverage, your insurance company steps in to pay for your medical expenses, lost wages, and other damages that the at-fault driver would have been responsible for.
There are two main parts to uninsured motorist coverage: Uninsured Motorist Bodily Injury (UMBI) and Uninsured Motorist Property Damage (UMPD). UMBI covers your injuries and the injuries of your passengers. UMPD covers damage to your vehicle. Not all states require UMPD, and some states allow you to purchase UMBI without UMPD. In many states, UMBI is mandatory unless you sign a waiver rejecting it in writing. This highlights just how important insurers and regulators consider this protection to be.
It is important to note that uninsured motorist coverage does not cover damage to the other driver's vehicle. It is purely for your protection and the protection of your passengers. If you are the at-fault driver, your liability coverage handles the other party's damages, not your UM coverage. UM coverage is triggered only when the other driver is at fault and lacks insurance. For a deeper dive into how this coverage functions in various scenarios, you can read our underinsured motorist coverage explained clearly guide, which provides additional context on related protections.
What Is Underinsured Motorist Coverage?
Underinsured motorist coverage (UIM) is similar to UM coverage, but it applies when the at-fault driver has some insurance, just not enough to cover the full extent of your damages. For example, suppose the other driver carries the state minimum liability limit of $25,000 per person for bodily injury. If you suffer $75,000 in medical bills, their insurance will pay only $25,000, leaving a $50,000 gap. Your underinsured motorist coverage would then kick in to cover the remaining $50,000, up to your policy's limits.
The definition of "underinsured" can vary by state, but generally, it means the at-fault driver's liability limits are less than your damages or less than your own UIM limits. Some states use a "difference" approach, where UIM pays the difference between the at-fault driver's limits and your UIM limits. Other states use a "gap" approach, which is more favorable to the injured party. Regardless of the method, the goal of UIM coverage is to fill the gap left by the other driver's inadequate insurance.
UIM coverage typically applies to bodily injury only, though some states also offer underinsured motorist property damage. It is usually sold in the same amounts as your uninsured motorist coverage, and in many states, you must purchase UM coverage before you can buy UIM. Like UM, UIM is designed to protect you and your passengers, not the other driver. It is a crucial layer of protection in a world where many drivers choose to carry only the bare minimum insurance required by law.
Key Differences Between Uninsured and Underinsured Motorist Coverage
While uninsured and underinsured motorist coverage are often discussed together, they address two distinct scenarios. The primary difference lies in the insurance status of the at-fault driver. Uninsured motorist coverage applies when the at-fault driver has no insurance at all. Underinsured motorist coverage applies when the at-fault driver has insurance, but their liability limits are insufficient to cover your damages. Both coverages are triggered by the other driver's fault, and both are designed to protect you from financial loss.
Another difference is the complexity of the claims process. Uninsured motorist claims are often more straightforward because there is no other insurance company involved. Underinsured motorist claims, however, can be more complicated because you may need to file a claim with the at-fault driver's insurer first, and then with your own insurer for the remaining balance. This coordination of benefits can sometimes lead to delays or disputes, but your insurance company is generally required to act in good faith.
Here is a quick breakdown of the key differences:
- Uninsured motorist coverage: Applies when the at-fault driver has no liability insurance or cannot be identified (hit-and-run).
- Underinsured motorist coverage: Applies when the at-fault driver has liability insurance, but the limits are too low to cover your damages.
- Claim process: UM claims are filed directly with your insurer; UIM claims may require filing with the at-fault driver's insurer first.
- Coverage limits: Both are typically sold in the same amounts as your liability coverage, but you can often purchase higher limits.
- State requirements: Many states require UM/UIM coverage unless you sign a waiver; others make it optional.
Understanding these differences can help you make informed decisions about your policy. It also helps you know what to expect if you ever need to file a claim. Many drivers are surprised to learn that their own insurance company will pay for their injuries under UM/UIM coverage, even though the other driver was at fault. This is because UM/UIM is a first-party coverage, meaning it covers you, the policyholder, regardless of fault.
How Uninsured and Underinsured Motorist Coverage Work Together
Uninsured and underinsured motorist coverage are often sold together as a package, and they work in tandem to provide comprehensive protection. If you are hit by an uninsured driver, your UM coverage responds. If you are hit by a driver with insufficient insurance, your UIM coverage responds. In both cases, your insurance company steps in to cover your damages up to your policy limits. This seamless integration is why many insurance professionals recommend purchasing both coverages at the same limits as your liability coverage.
It is also important to understand how these coverages interact with your health insurance. If you have health insurance, it may cover your medical bills initially. However, your health insurer may later seek reimbursement from your UM/UIM settlement. This is known as subrogation. In some states, you can purchase "medical payments" coverage or "personal injury protection" (PIP) to cover medical expenses regardless of fault, which can reduce the need to rely on UM/UIM for smaller injuries. However, for serious accidents, UM/UIM remains essential.
Another key point is that UM/UIM coverage follows you, not your car. If you are injured as a passenger in someone else's car, or if you are hit by a car while walking or riding a bike, your UM/UIM coverage may still apply. This portability makes it a valuable safety net in various situations. It is also worth noting that UM/UIM coverage typically does not cover damage to your vehicle unless you have UMPD or collision coverage. For vehicle damage, you would need to rely on collision coverage or UMPD, if available.
Why You Need Both Coverages
The number of uninsured drivers on the road is staggering. According to the Insurance Research Council, about one in eight drivers in the United States is uninsured. In some states, the rate is as high as one in four. Even if you are a safe driver, you cannot control the actions of others. If you are involved in an accident with an uninsured driver, you could be left paying thousands of dollars out of pocket for medical bills, lost wages, and vehicle repairs. UM coverage protects you from this financial burden.
Underinsured motorist coverage is equally important because many drivers who do carry insurance purchase only the minimum limits required by law. These minimums are often as low as $25,000 per person and $50,000 per accident for bodily injury. A serious accident can easily exceed these limits, leaving you with significant unpaid bills. UIM coverage fills this gap, ensuring that you are not stuck with the difference. Without UIM, you would have to sue the at-fault driver personally, which is often futile if they have limited assets.
Purchasing both coverages is relatively inexpensive compared to the potential financial devastation of an accident with an uninsured or underinsured driver. The cost is typically a small fraction of your total premium, yet the protection it offers is immense. When you consider the alternative, which is potentially facing bankruptcy or years of debt, the value of UM/UIM coverage becomes clear. It is one of the smartest investments you can make in your auto insurance policy.
How to Choose the Right Limits
When deciding on UM/UIM limits, a good rule of thumb is to match them to your liability coverage limits. If you carry $100,000 per person and $300,000 per accident in bodily injury liability, you should carry the same amount in UM/UIM. This ensures that you are protected to the same extent that you are protecting others. Some insurers offer higher limits, and if you have significant assets or income to protect, you may want to consider purchasing more. The cost of increasing UM/UIM limits is usually modest.
It is also important to check your state's requirements. Some states require UM/UIM coverage, while others make it optional. In states where it is optional, you may be asked to sign a waiver rejecting it. Before you sign that waiver, consider what you would do if you were hit by an uninsured driver. The few dollars you save each month could cost you tens of thousands of dollars in the long run. It is almost always worth keeping the coverage.
If you are unsure about the right limits for your situation, you can use online resources to compare quotes and coverage options. For example, FreeAutoInsuranceQuotesOnline is a consumer education platform that helps drivers understand coverage options and compare rates from multiple carriers. You can also consult with a licensed insurance agent who can review your policy and make recommendations based on your assets, income, and risk tolerance. The goal is to find a balance between affordability and adequate protection.
Common Myths About Uninsured and Underinsured Motorist Coverage
There are several myths surrounding UM/UIM coverage that can lead drivers to make poor decisions. One common myth is that if you have health insurance, you do not need UM/UIM coverage. While health insurance can cover medical bills, it does not cover lost wages, pain and suffering, or other non-medical damages. UM/UIM coverage can provide compensation for these losses, which health insurance does not. Additionally, health insurers may have deductibles and co-pays that can add up quickly.
Another myth is that UM/UIM coverage is only for accidents involving other cars. In reality, UM/UIM coverage can apply if you are hit by a car while walking or riding a bike, or if you are a passenger in a vehicle that is struck by an uninsured driver. It can also apply if you are the victim of a hit-and-run. The coverage is designed to protect you as an individual, not just as a driver. This broad applicability makes it an essential part of your insurance portfolio.
A third myth is that UM/UIM coverage is too expensive. In reality, it is often one of the most affordable coverages on your policy. The exact cost depends on your state, your driving record, and the limits you choose, but it is typically much less than collision or comprehensive coverage. Given the potential financial impact of an accident with an uninsured or underinsured driver, the cost is well worth it. Many drivers find that they can add UM/UIM coverage for just a few dollars a month.
Steps to Take If You Are Hit by an Uninsured or Underinsured Driver
If you are involved in an accident with an uninsured or underinsured driver, it is important to take the following steps to protect your rights and ensure a smooth claims process:
- Call the police: A police report can help establish fault and document the accident. It is also required in many states for insurance claims.
- Exchange information: Get the other driver's name, contact information, license plate number, and insurance information if available. If they are uninsured, they may not have insurance cards, but you should still get their contact details.
- Document the scene: Take photos of the damage to all vehicles, the accident scene, and any visible injuries. Collect contact information from witnesses.
- Notify your insurer: Report the accident to your insurance company as soon as possible. Let them know that the other driver was uninsured or underinsured and that you intend to file a UM/UIM claim.
- Seek medical attention: Even if you feel fine, see a doctor. Some injuries, like whiplash or concussions, may not be immediately apparent. Medical records are also important for your claim.
- Keep detailed records: Keep all receipts, medical bills, and correspondence related to the accident. This documentation will be needed for your claim.
Following these steps can help you build a strong case and ensure that you receive the compensation you deserve. It is also a good idea to consult with a personal injury attorney if you have serious injuries or if your insurance company disputes your claim. An attorney can help you navigate the complex process and advocate for your rights.
The Bottom Line
Uninsured vs underinsured motorist coverage may sound like a minor distinction, but it can make a world of difference when you are involved in an accident. Uninsured motorist coverage protects you when the at-fault driver has no insurance, while underinsured motorist coverage protects you when the at-fault driver has insurance that is insufficient to cover your damages. Both are essential for any driver who wants to avoid financial ruin after an accident. By understanding how they work and choosing the right limits, you can drive with confidence knowing that you are protected.
When you are ready to review your policy or get quotes from multiple carriers, consider using a service that connects you with licensed insurance agents. NewAutoInsurance.com is an independent online resource that provides consumer guidance and educational content. It is not an insurance carrier or broker, but it can help you explore your options and find potential savings. Taking the time to ensure you have adequate UM/UIM coverage is one of the most responsible decisions you can make as a driver.